
Helping Family Financially Without Missing Your Own Bills
The short answer
Before promising money, check what your household can provide without relying on repayment to cover its own essentials. Be clear about whether help is a gift, a loan or a recurring arrangement. Write down the amount, timing and what happens if circumstances change.
The CFPB recommends discussing expectations before family money changes hands, including whether repayment is expected and how the arrangement affects both people. CFPB family lending and borrowing guidance.
You can care about the person and still need time to check the numbers. “Let me look at what is already committed” is a reasonable first answer after a request arrives during a shift.
Test the help against money already assigned
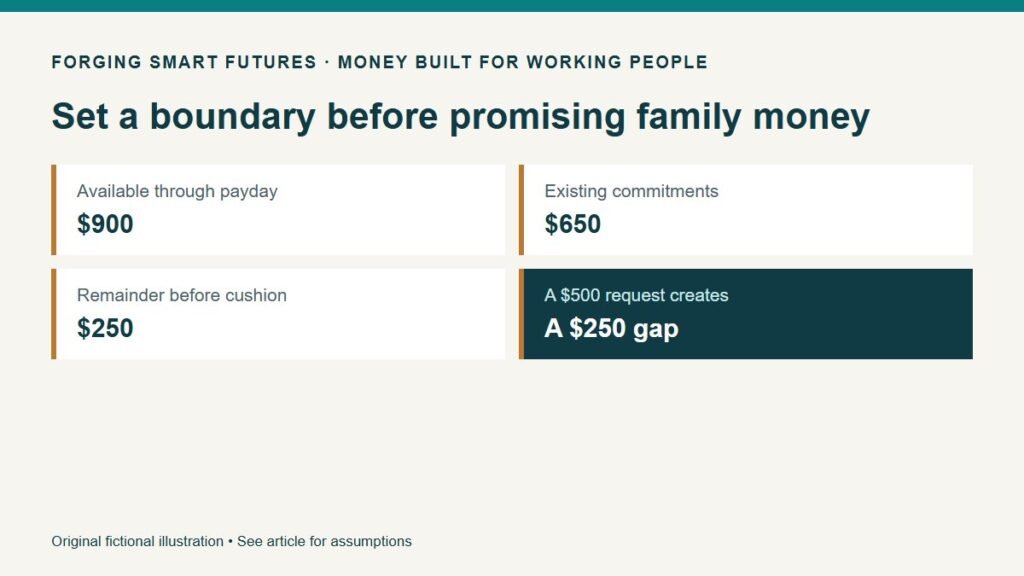
Suppose, in a fictional household, $900 is available until the next reliable payday. Groceries and transportation need $220, utilities need $180, and $250 must remain for a known insurance bill. That leaves $250 before any additional cushion or omitted expense.
A request for $500 does not fit this plan. A promise to repay next week does not change the cash required if repayment is late. Sending $500 would leave a $250 gap relative to these listed commitments. The calculation is a boundary check, not an instruction that the full $250 remainder should be given away.
If the available amount is zero, state that honestly. You might still offer transportation, help comparing bills, a meal or time finding assistance. Put limits on noncash help too if it costs fuel, childcare or missed work.
Name the arrangement clearly
A gift does not carry an expectation of repayment. A loan does. Do not say “pay me when you can” while privately counting on the money for rent in two weeks. That mismatch can hurt both the relationship and the budget.
For ongoing support, specify the amount, frequency and review date. “I can contribute $75 on each of the next two Fridays, then we need to reassess” is clearer than “I'll help until things improve.” Avoid promises based on uncertain overtime.
If lending, discuss the repayment schedule, a missed-payment plan and how you will communicate. Keep a written record both people understand. This article does not provide a legally enforceable loan agreement or determine tax treatment; larger or complex arrangements warrant appropriate professional help.
Do not borrow a problem you cannot carry
Taking out a loan, handing over a card or signing for another person's obligation is different from giving a fixed amount of available cash. Before agreeing, understand the contract and what you could owe if the other person cannot pay. Do not assume a private promise changes the creditor's rights under the signed agreement.
Ask yourself: could I carry the entire obligation without repayment? What would happen to transportation, housing or required bills? If the answer is unknown, do not treat the arrangement as a small favor.
Keep personal account access separate. Helping someone pay a bill does not require sharing your login or giving them unrestricted access to an account. Agree on the specific task and amount.
Have the follow-up conversation before it becomes urgent
Set a check-in date that fits both schedules. If a payment is late, first establish the facts rather than building your own next bills around another verbal assurance. Update the household plan using money actually received.
If you choose to change the arrangement, write the change down. Do not quietly convert a loan into an ongoing subsidy while your own finances deteriorate. A clear limit can preserve a relationship better than repeated promises followed by resentment.
Use the FSF bill-calendar guide before responding to the next request. The free checklists in Resources can help you identify existing commitments. Start by offering what your actual plan supports, not what a better-pay month might have supported.
General financial education, not individualized financial, investment, tax, legal or credit advice. Example is fictional. No affiliate relationship is included.
Editorial attribution: Paul Foster
Published: September 10, 2026 Last reviewed: September 10, 2026
Sources & References
- https://www.consumerfinance.gov/consumer-tools/educator-tools/adult-financial-education/tips-for-managing-family-lending-and-borrowing/
Put this into practice
Compare the full commitment against a lower-income month. Free Major Financial Decisions checklist — no membership required.
Related decisions
- Cash, Payment Plan or Loan for an Urgent Home Repair?
- Lease or Buy a Vehicle When Work Puts on Heavy Mileage?
- Term Life Insurance When Your Family Depends on Your Paycheck
Expanded member resource: Big Purchase and Household Decision Workbook. Guided exercises with local save, reopen and print controls. Worksheet answers are not automatically calculated. Compare free resources and FSF membership benefits.
Human-reviewed, AI-assisted content; how FSF creates articles.