
Find and Organize Old Accounts Before Making a New Money Plan
The short answer
Start with a list of past employers and financial providers, gather records, contact each institution independently and record what is confirmed. Search official unclaimed-property and retirement resources for gaps. Finding an account is a different decision from withdrawing, closing or rolling it over.
A worker who has changed contractors, plants or employers several times may have paperwork under old company names and addresses. The task is to rebuild a reliable map, not move everything in one afternoon.
Build an employment and household timeline
List employer names, approximate years, former addresses and any plan or bank names remembered. Gather old statements, tax records and benefit notices you already possess. Mark uncertain dates instead of inventing precision.
For each lead, record the institution, account type if known, evidence date, verified contact route and next action. Use only a partial account reference in the working list. Keep sensitive documents and credentials in appropriate private storage.
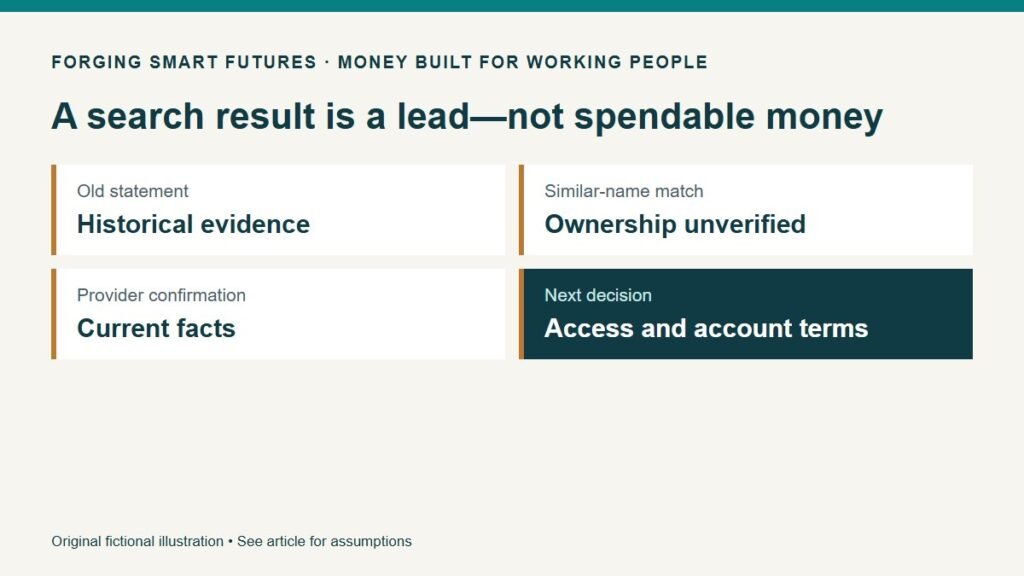
An old account balance is historical evidence, not money available now. The account may have changed providers, been transferred, distributed or affected by fees and market movements. Ask for current confirmation.
Contact providers through independent routes
Use an official website or verified statement contact, not a number from an unsolicited “we found your money” message. Ask how to verify identity securely, whether the account still exists and who now administers it.
For an old workplace plan, the former employer or plan administrator may help identify its current provider. A corporate acquisition or renamed employer can make this step more complicated. Keep the original employer name and approximate dates available.
The Department of Labor's Retirement Savings Lost and Found helps users search for retirement-plan contact information. Review its coverage, identity-verification process and limitations on the official site. A result is a lead to investigate; a missing result does not prove no benefit exists.
Search the right official database for the missing item
USAGov explains that there is no single database for all unclaimed money. It links to state unclaimed-property offices and separate resources for items such as pensions, bank failures and matured savings bonds. Check states where you previously lived as well as your current state. USAGov unclaimed-money guide.
Keep a search log: site used, date, name/address variations searched and follow-up needed. Do not pay an unsolicited recovery service merely because it found the same public listing. Follow the official holder's claim process and verify any request for identity documents.
If searching for a deceased relative's property, do not assume being related is enough to claim it. The holder will specify authority and documentation requirements. Get appropriate help when ownership or estate authority is unclear.
Use evidence levels in the inventory
Here is an original fictional example:
| Item | What is known | How to treat it |
|---|---|---|
| Old plan statement showing $8,000 | Statement is five years old | Historical lead; request current information |
| Bank confirms current $240 balance | Identity and ownership verified | Record current access and restrictions |
| Search result with a similar name | Ownership not established | Possible match; no amount added to budget |
Adding all three as cash available today would overstate certainty. Keep “historical,” “possible match” and “confirmed current” visibly separate.
Organize first; decide second
For a confirmed account, record current value, fees, access, beneficiary information to review and outstanding questions. Before moving a retirement account, investigate taxes, plan features, protections and rollover options. Before closing a bank account, identify linked deposits and payments.
Set one follow-up date for each unresolved item. A half-finished search is easier to resume when the next contact is documented. Revisit the inventory after job changes, moves or major household changes.
Use the free Starting Over checklist in FSF Resources to organize next actions. Keep the bill-calendar plan based on verified accessible money while the search continues.
General financial education, not individualized financial, investment, tax, legal or credit advice. Examples are fictional. No recovery or account balance is guaranteed, and no affiliate relationship is included.
Editorial attribution: Paul Foster
Published: September 10, 2026 Last reviewed: September 10, 2026
Sources & References
- https://lostandfound.dol.gov/
- https://www.usa.gov/unclaimed-money
Put this into practice
Make the next few weeks manageable before rebuilding the long term. Free Starting Over / Late-Starters checklist — no membership required.
Related decisions
- Can You Afford a Career Change Later in Life? Build a Transition Budget
- A Payday Routine for Rebuilding Financial Confidence
- Rebuilding After Divorce: Organize the Accounts Before Making New Commitments
Expanded member resource: Financial Restart Organizer. Guided exercises with local save, reopen and print controls. Worksheet answers are not automatically calculated. Compare free resources and FSF membership benefits.
Human-reviewed, AI-assisted content; how FSF creates articles.