
A Payday Routine for Rebuilding Financial Confidence
The short answer
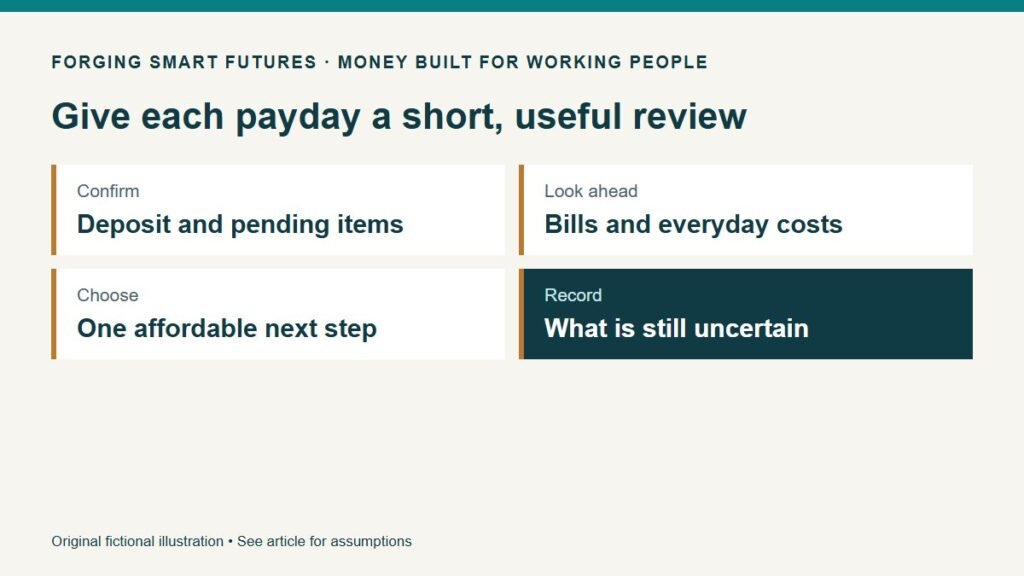
On payday, confirm the money received, review what must happen before the next dependable deposit and assign cash before making optional transfers or purchases. End by writing one next action. The routine should be short enough to repeat after a tiring week and complete enough to catch a bill-timing problem.
This is a maintenance routine for a plan you are rebuilding. It is not a promise that good organization can solve inadequate income or an unaffordable obligation by itself.
Prepare once so payday is easier
Keep the bill calendar, recent pay statement and list of automatic withdrawals together. Record the normal pay schedule and any known payroll delay. Use a private location appropriate for financial information; do not put passwords into a shared household worksheet.
The CFPB's cash-flow budgeting approach connects starting cash, incoming money and spending across time. The practical routine below applies that idea to payday decisions. CFPB Your Money, Your Goals toolkit.
If two people share bills, decide who updates the record and who makes each payment. Two people independently “taking care of the same bill” can create a duplicate payment or leave each assuming the other handled it.
First, confirm the deposit and existing commitments
Check the actual deposit against the pay statement. Note an unexpected deduction, missing hours or reimbursement separately and contact the appropriate person. Until corrected, plan with the cash actually available.
Next, review pending transactions and automatic payments. The displayed balance may include money already committed. Mark bills as scheduled, paid or posted; those labels represent different stages. Do not issue another payment simply because the first has not yet appeared as posted.
Then look through the next reliable payday
List formal bills plus food, fuel, transit, childcare and other essentials. Look a few days beyond the window for a large bill that the next check cannot cover alone. Include an amount for known irregular expenses if the plan calls for it.
In a fictional pay period, starting usable cash is $120 and the new deposit is $1,480, giving $1,600. Planned bills need $900, everyday essentials $320 and an annual-bill reserve $150. That leaves $230 before any additional cash cushion or optional goal.
The $230 is not automatically spending money. Check omitted costs and the following pay window. If the household chooses to keep $130 available for uncertainty in this example, $100 remains for the selected next step. These amounts illustrate the process, not a recommended reserve size.
Choose one affordable next move
The move might be an extra debt payment, a savings transfer, replacing needed work gear or simply keeping cash available during unstable hours. Record the purpose and amount. If the next-payday plan is short, the next move may instead be a call about a bill.
Avoid scattering a small remainder among many goals merely to make the worksheet look balanced. It is more useful to understand the chosen tradeoff and revisit it next payday. Do not schedule a recurring amount based on one unusually strong check.
Finish with a brief written handoff
Write three lines: what is covered, what is still uncertain and who will do what next. For example: “Utilities scheduled; overtime correction not received; contact payroll Tuesday.” This makes it possible to resume without rebuilding the whole picture from memory.
Set the next review date. If a major bill, hours reduction or account issue occurs first, update the plan then rather than waiting for the routine. Automation can handle a reminder; it cannot know that a shift was canceled unless someone updates the assumptions.
Judge the routine by fewer surprises
After several pay cycles, ask whether you can identify the next due dates, find payment confirmations and explain the cash still available. If the routine is too elaborate to maintain, remove decorative tracking and retain the facts that change a decision.
Use the FSF biweekly bill-calendar guide and free Starting Over checklist in Resources. Expanded member workbooks offer more structured space, but a simple written record can start the habit today.
General financial education, not individualized financial, investment, tax, legal or credit advice. Example is fictional. No affiliate relationship is included.
Editorial attribution: Paul Foster
Published: September 10, 2026 Last reviewed: September 10, 2026
Sources & References
- https://www.consumerfinance.gov/consumer-tools/educator-tools/your-money-your-goals/toolkit/
Put this into practice
Make the next few weeks manageable before rebuilding the long term. Free Starting Over / Late-Starters checklist — no membership required.
Related decisions
- Rebuilding After Divorce: Organize the Accounts Before Making New Commitments
- Returning to Work After Caregiving: Budget the Gap Before the First Paycheck
- Catch-Up Saving Without Catch-Up Scams: Evaluate Big-Promise Offers
Expanded member resource: Financial Restart Organizer. Guided exercises with local save, reopen and print controls. Worksheet answers are not automatically calculated. Compare free resources and FSF membership benefits.
Human-reviewed, AI-assisted content; how FSF creates articles.