
Catch-Up Saving Without Catch-Up Scams: Evaluate Big-Promise Offers
The short answer
Treat pressure to make up lost time as a reason to slow the decision down. Ask what return the offer actually requires, what can go wrong, how the seller is paid and how you can independently verify the people and product. A retirement shortfall does not make an unusually high return more likely.
The SEC identifies high guaranteed returns, low-risk claims and urgency as warning signs of investment fraud. Registration checks are useful, but they are not a guarantee of safety or suitability. SEC investment-scam guidance.
Translate the headline into an annual claim
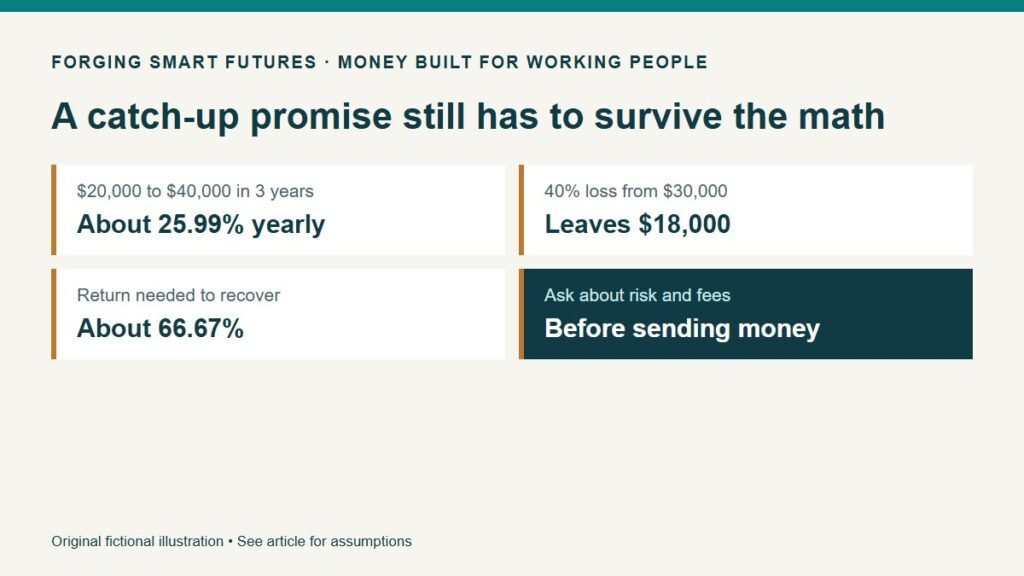
Suppose a fictional promotion says $20,000 can become $40,000 in three years without more contributions. Doubling in that period requires about 25.99% compounded annually before fees and taxes: the cube root of two minus one.
That arithmetic does not prove a specific offer is fraudulent. It reveals the performance being implied so you can ask what risks could support it and whether the seller presents them honestly. A phrase such as “conservative catch-up strategy” does not change the calculation.
If the illustration actually includes $5,000 in new contributions each year, the increase is not all investment return. Demand a clear separation of deposits, gains, fees and withdrawals before comparing it with another plan.
Identify what you are being sold
Write the product's legal name, issuer, seller, custodian, fees, withdrawal restrictions and the documents explaining risks. Ask where money is sent and who can authorize transfers. Do not accept a dashboard balance or a testimonial as proof that assets exist or can be withdrawn.
An educational course, investment product, insurance contract and managed account are different purchases. If the pitch shifts between them, ask which agreement you are actually signing and what each charge buys.
Use contact information found independently through official records, not only a link or phone number in the pitch. A real firm's name can be copied by someone unrelated to it.
Test the downside against your remaining working years
In a fictional $30,000 account, a 40% loss leaves $18,000. Returning from $18,000 to $30,000 requires a 66.67% gain before fees or taxes. A claim that you can simply “earn it back” may conceal how difficult recovery becomes after a large loss.
Ask what happens if the money cannot be withdrawn when your hours are reduced or retirement begins earlier than planned. Consider whether the investment depends on selling at an uncertain price, finding another buyer or accepting a surrender charge.
Do not borrow against essential assets or cash out retirement money merely because a salesperson says delay is your biggest risk. Those actions can create debt or tax consequences before the investment has produced anything.
Compare the price of the promise
A fictional $2,000 coaching or access fee consumes 10% of a $20,000 savings balance immediately. The remaining $18,000 would need an 11.11% gain just to restore the original $20,000, ignoring taxes and further costs.
That does not mean every paid education service is a scam. It means the fee should be evaluated for concrete deliverables, documented qualifications, refund terms and alternatives, not treated as an investment return itself. Do not assume a refund promise is easy to enforce or covers market losses.
Use a decision pause with specific checks
Save the offer, verify the seller and product independently, read the written risks and fees, and discuss unresolved questions with a qualified professional who is not being paid to sell that offer. If the seller discourages independent review or demands secrecy, stop the transaction process while investigating.
If money has already been sent and fraud is suspected, contact the relevant financial institution promptly and use official reporting channels. Be wary of a second party demanding upfront fees to recover the money. FTC scam-response steps, FTC recovery-scam guidance.
Your next action
Write the implied return and the amount you could lose before evaluating a catch-up pitch. Focus the household plan on sustainable contributions and verified benefits using the FSF match guide and variable-pay budget. Existing planning materials are labeled on the Resources page.
General education, not individualized investment, legal or tax advice. Examples are fictional, not forecasts or fraud determinations. No product, recovery outcome or affiliate relationship is endorsed.
Editorial attribution: Paul Foster
Published: September 10, 2026 Last reviewed: September 10, 2026
Sources & References
- https://www.investor.gov/protect-your-investments/fraud/protect-your-money
- https://consumer.ftc.gov/articles/what-do-if-you-were-scammed
- https://consumer.ftc.gov/articles/refund-and-recovery-scams
Put this into practice
Make the next few weeks manageable before rebuilding the long term. Free Starting Over / Late-Starters checklist — no membership required.
Related decisions
- Starting Over Financially: A First-30-Days Plan for Working Adults
- Your Hours Were Cut: What to Review Before the Next Payday
- Find and Organize Old Accounts Before Making a New Money Plan
Expanded member resource: Financial Restart Organizer. Guided exercises with local save, reopen and print controls. Worksheet answers are not automatically calculated. Compare free resources and FSF membership benefits.
Human-reviewed, AI-assisted content; how FSF creates articles.