
Target-Date Fund or a Few Index Funds in Your Workplace Plan?
The short answer
A target-date fund offers a managed investment mix that changes over time. A set of index funds lets you choose and maintain the mix yourself. Compare the actual holdings, risk, costs and maintenance work rather than assuming either label guarantees the better choice.
These categories also overlap: a target-date fund may invest in index funds. The useful comparison is often a managed allocation versus an allocation you are responsible for maintaining.
Look beyond the year in the name
The SEC explains that target-date funds typically change their allocation over time, following a glide path. Some continue changing after the target year. Funds with similar dates can have different strategies and risks, and the date does not guarantee enough money for retirement. SEC target-date fund bulletin.
Ask the plan for the actual investment description. Some workplace target-date options are collective investment trusts rather than SEC-registered mutual funds; the SEC bulletin's scope is mutual funds and ETFs. Use the documentation for the option actually in your plan.
Record the current stock/bond mix, how it changes, underlying investments and total disclosed costs. Do not infer these from the retirement year alone.
Decide who will maintain the allocation
With a small index-fund portfolio, you choose percentages and a review method. If markets move the percentages away from your plan, decide how and when to rebalance. You also need to check whether the funds actually cover the exposures you intended.
For someone working rotating shifts, a simpler maintained arrangement may be useful. But “simple” is not the same as suitable. A convenient fund can still have a risk level that does not fit your timeline or circumstances.
SEC allocation guidance connects the investment mix to time horizon and risk tolerance and explains why diversification requires looking beyond the number of funds. SEC asset allocation guidance.
Compare costs in dollars, with the same assumptions
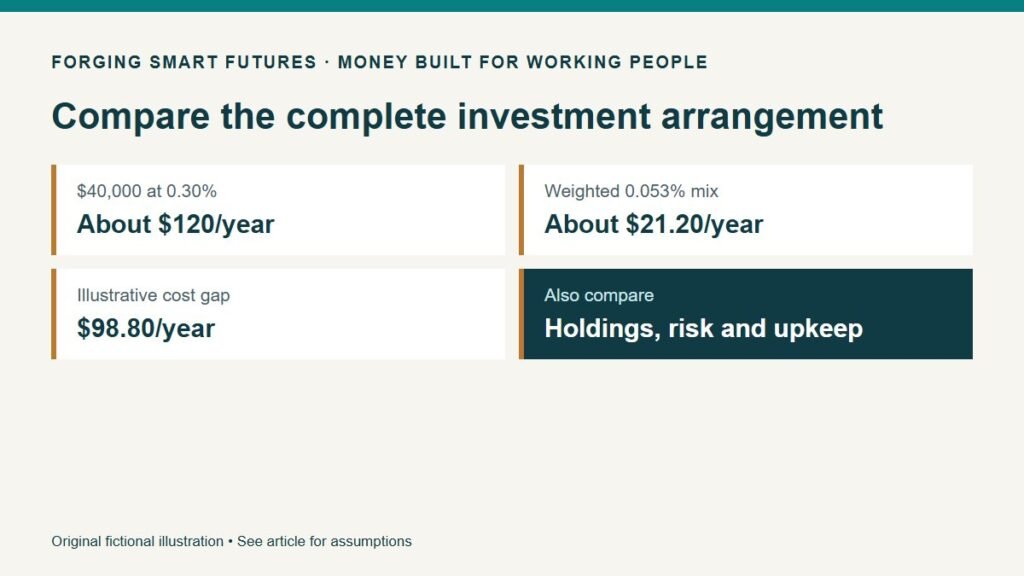
Consider a fictional $40,000 account. A target-date option with an annual expense rate of 0.30% corresponds to about $120 on a constant balance. A three-fund mix with 60% at 0.04%, 30% at 0.08% and 10% at 0.05% has a weighted rate of 0.053%, about $21.20 on the same constant balance.
The illustrative difference is $98.80 per year. Actual expenses depend on changing balances and the funds' arrangements; other plan or advice fees may also apply. This calculation does not show that the cheaper mix has equivalent holdings, risk or services. It also does not value the work of maintaining it.
Read the fee disclosure to avoid adding underlying expenses twice if the disclosed total already includes them. Use actual plan options, not a low fee advertised for a fund share class your plan does not offer.
Check the combined portfolio
If you put half the account in a target-date fund holding 60% stocks and half in an all-stock fund, the combined stock exposure is 80%: 30 percentage points from the first half plus 50 from the second. Adding a stock fund did not create a second independent retirement strategy; it changed the total allocation.
That fictional example is not a recommended mix. It shows why combining options without examining holdings can defeat the balance you thought you selected. Include other retirement accounts and significant employer stock in the review.
Make a maintenance decision you can follow
Write the intended mix, reason for it, total cost and review trigger. If choosing the managed option, understand what it manages and what remains your responsibility. If choosing individual funds, put the review on a schedule you will actually keep and avoid changing it solely because last month's winner looks attractive.
Your next action
Request the plan's investment and fee disclosures and compare two complete arrangements, not isolated fund names. Review your FSF employer-match questions separately. Existing free and member materials are listed on the Resources page.
General education, not individualized investment advice. All allocations, balances and fees are fictional. Investments can lose value; no fund, return or affiliate relationship is endorsed.
Editorial attribution: Paul Foster
Published: September 10, 2026 Last reviewed: September 10, 2026
Sources & References
- https://www.investor.gov/introduction-investing/general-resources/news-alerts/alerts-bulletins/investor-bulletins/target-date-funds-investor-bulletin
- https://www.investor.gov/introduction-investing/getting-started/asset-allocation
Put this into practice
Prepare better questions before choosing an account or investment. Free Investing checklist — no membership required.
Related decisions
- Company Stock in Your Retirement Plan: Your Job and Savings Can Share a Risk
- Investing During a Market Drop When Your Overtime Has Also Disappeared
- Your First Investing Steps When There Is Finally Room in the Paycheck
Expanded member resource: Investing Foundations Research Workbook. Guided exercises with local save, reopen and print controls. Worksheet answers are not automatically calculated. Compare free resources and FSF membership benefits.
A simple portfolio framework: Our Bogleheads-style investing guide explains broad diversification, low costs, Fidelity fund examples and the limits of historical returns. Compare your own assumptions in its free scenario explorer.
Human-reviewed, AI-assisted content; how FSF creates articles.