
Debt Snowball or Avalanche When Your Extra Pay Changes Each Month?
The short answer
The snowball puts extra money toward the smallest balance; the avalanche targets the highest interest rate. Either can accept irregular extra payments. The essential first step is protecting required payments and household cash, then deciding where each affordable extra dollar goes.
You do not need the same overtime check every month to follow a consistent strategy. Consistency can mean using the same decision rule whenever extra money is available.
Separate the amount from the destination
There are two decisions. First, how much extra can the household afford after essentials, required payments and its cash reserve? Second, which debt receives it? A payoff calculator may answer the second question while assuming you already solved the first.
Use the FSF variable-pay budget to set the available amount. Do not use next month's hoped-for overtime to make this month's strategy look feasible.
The CFPB describes both approaches and their tradeoff: the smallest balance can provide a visible completion milestone; directing extra money to the most expensive debt can reduce interest costs. CFPB debt action plan.
Compare one extra payment before forecasting years
Consider these fictional balances after required payments have already been handled:
| Debt | Balance | Annual interest rate |
|---|---|---|
| A | $600 | 12% |
| B | $2,000 | 28% |
| C | $4,000 | 18% |
A $300 extra payment goes to A under the snowball and B under the avalanche. For a simplified one-month comparison, assume unchanged rates and approximate interest as balance × annual rate ÷ 12. Reducing A by $300 avoids about $3 of that month's interest; reducing B by $300 avoids about $7. The difference is about $4 for that month alone.
Real statements may use daily balances, payment dates and other terms. This calculation is not a lender payoff quote or a full repayment simulation. It isolates why rate matters. Meanwhile, paying A reduces its remaining principal to $300, much closer to closing out that particular balance. The emotional and administrative benefit may matter to someone managing bills between rotating shifts.
Stress-test the lean month
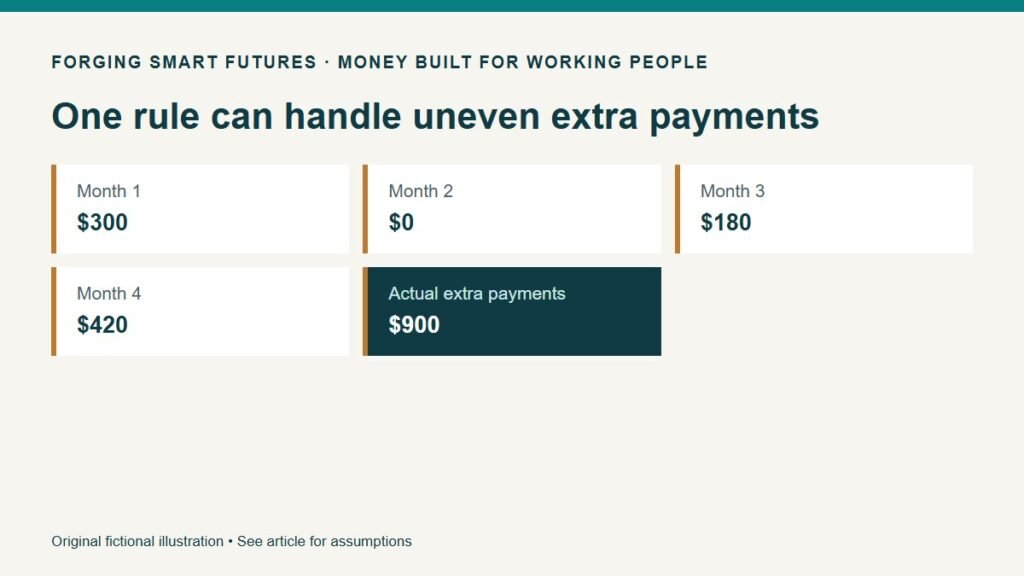
Suppose affordable extra payments over four months are $300, $0, $180 and $420. They total $900, averaging $225. A plan that schedules $225 automatically every month would require $225 in the zero-extra month that this scenario does not have.
Instead, maintain required payments and apply the actual affordable extra amount when it becomes available. If the target debt is cleared, get the current payoff figure and direct any genuinely remaining money to the next debt. Do not send money twice because a calculator and an automatic payment both assume they own the same dollars.
Keep a short record: statement balance, rate, minimum, due date, target rank, payment sent and payment posted. Update the ranking after rate changes or promotional periods end. The strategy should follow current terms, not last year's spreadsheet.
When the ranking is the wrong first question
If you cannot cover all minimums or essential bills, pause the comparison and identify the immediate shortfall. Contact affected creditors and ask what arrangements are available, what they cost and how they affect the account. An “extra-payment strategy” cannot repair a budget that lacks enough for required payments.
A special promotional balance also deserves its own terms review. Do not assume a quoted zero rate, deferred-interest arrangement and ordinary fixed-rate balance behave the same way. Put the expiration date and contractual consequences beside the rate before deciding on a target.
Choose a rule you can explain
Write one sentence: “After essentials and required payments, my extra debt money goes to ___ because ___.” Review it after three actual pay cycles. Did you keep the needed cash? Did the payment post correctly? Did the system reduce confusion? A strategy that exists only in an idealized forecast needs adjustment.
Start with the free Debt & Credit checklist through FSF Resources. Members can compare scenarios in the expanded resource library. Neither an example nor a calculator can guarantee a payoff date when future pay, rates and spending are uncertain.
General financial education, not individualized financial, investment, tax, legal or credit advice. All numerical examples are fictional. No affiliate relationship or compensated recommendation is included.
Editorial attribution: Paul Foster
Published: September 10, 2026 Last reviewed: September 10, 2026
Sources & References
- https://files.consumerfinance.gov/f/documents/cfpb_your-money-your-goals_debt-action-plan_tool_2018-11.pdf
Put this into practice
Put balances, dates and written terms in one usable plan. Free Debt & Credit checklist — no membership required.
Related decisions
- Balance Transfer or Consolidation Loan? Compare the Whole Payoff Job
- Should Your Next Overtime Check Go Toward Debt or Your 401(k)?
- Buy Now Pay Later for Tools and Work Gear: Add Up Every Due Date
Expanded member resource: Debt Organization and Decision Workbook. Guided exercises with local save, reopen and print controls. Worksheet answers are not automatically calculated. Compare free resources and FSF membership benefits.
Human-reviewed, AI-assisted content; how FSF creates articles.