
Should Your Next Overtime Check Go Toward Debt or Your 401(k)?
The short answer
First check whether the money is needed for essential bills, debt minimums or a near-term cash gap. Then compare the employer match you can actually receive with the cost and terms of your debt. The choice does not have to be all debt or all retirement, and an overtime check does not have to create a permanent contribution you cannot afford on regular hours.
FINRA's financial-foundations guidance connects cash flow, emergency reserves and debt with the ability to invest. It does not provide a universal allocation for your paycheck. FINRA financial foundations.
Identify the amount that is genuinely available
Use deposited take-home pay for the cash plan, not gross overtime from the timesheet. Check bills due before the next reliable deposit and irregular costs already approaching. Paying down a card and then using it again for work transportation may leave you with little progress and less flexibility.
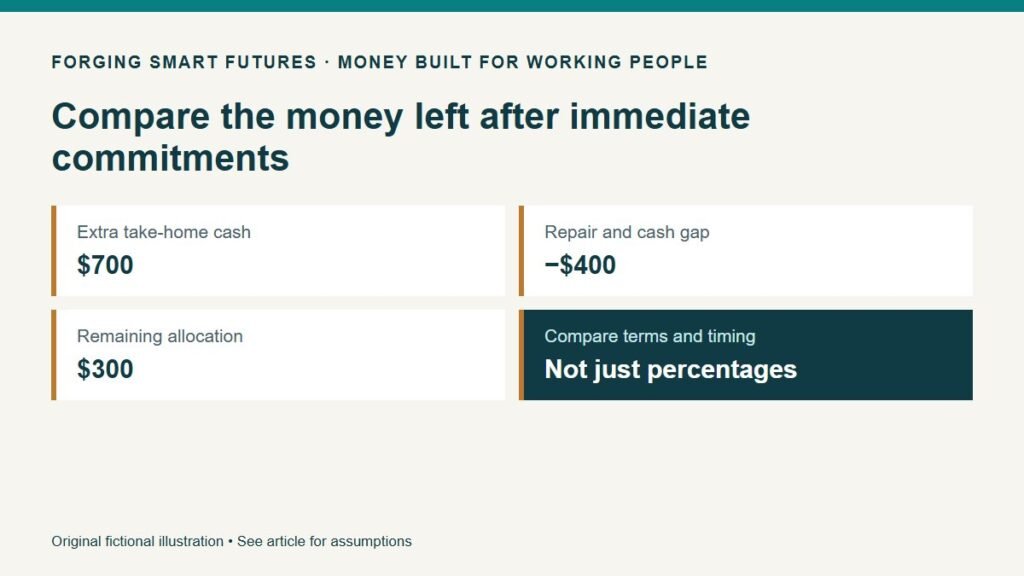
In a fictional example, an overtime-heavy check leaves $700 above the household's ordinary plan. A needed vehicle repair requires $250, and you decide to retain $150 for an identified cash gap. The remaining allocation question concerns $300, not the whole $700.
Those reserve amounts are fictional choices, not recommended minimums. What matters is naming the obligations before treating the entire extra deposit as spare money.
Read the match before comparing percentages
Find the matching formula, eligible compensation, vesting terms, contribution timing and any year-end adjustment rules in your actual plan. Confirm whether overtime counts and whether a change will apply to the next paycheck. The FSF match guide walks through those questions.
A fictional plan matches fifty cents per dollar on a specified portion of eligible employee contributions. If an additional $200 qualifies, the potential employer contribution is $100. But a quoted fifty-percent match is not a fifty-percent annual investment return. It is a contribution under plan rules, potentially affected by vesting, and the invested balance can gain or lose value.
Payroll contributions also are not normally made by depositing the overtime check from your bank account into the 401(k). You change the payroll election under the plan's process. That can affect future take-home pay, so ask payroll when the change starts and test the resulting household cash flow.
Compare debt cost over a stated period
For illustration, paying an extra $200 against a balance charging 24% annual interest avoids roughly $4 of interest over one month under a simple annual-rate-divided-by-twelve estimate. Actual card interest depends on the balance, timing and agreement.
That one-month interest estimate cannot be directly compared with the $100 employer contribution as though both were equivalent annual returns. Write down the time period, conditions and liquidity limits for each benefit. Paying down debt reduces what you owe; retirement money has access and tax rules that differ from ordinary cash.
If a payment is overdue or a promotional rate is expiring, those terms may change the urgency. If all matching contributions are already being captured, the next unmatched dollar presents a different comparison from a dollar that qualifies for more employer money.
Make a decision that survives a normal-pay month
Write three options: extra debt payment, additional payroll contribution or a split. For each, show the cash available before the next bill, expected debt balance, possible match and unresolved plan questions. Do not insert a guaranteed market return into the retirement column.
Choose a review trigger such as a change in hours, debt rate or match eligibility. If you raise contributions for a busy season, record when to check whether that rate still fits. A temporary overtime peak should not quietly become a household shortfall.
Your next action
Gather one current debt statement, the next bill dates and your plan's matching rules. Calculate the money left after immediate commitments before selecting an option. Use the free tools and clearly labeled member resources on the FSF Resources page to document the decision, and revisit the variable-pay budget when hours change.
General education, not individualized investment, tax, debt or financial advice. All examples are fictional; investment returns are uncertain. No affiliate relationship is presented.
Editorial attribution: Paul Foster
Published: September 10, 2026 Last reviewed: September 10, 2026
Sources & References
- https://www.finra.org/investors/investing/investing-basics/financial-foundations
Put this into practice
Turn plan documents and old statements into specific next steps. Free Retirement checklist — no membership required.
Related decisions
- Buy Now Pay Later for Tools and Work Gear: Add Up Every Due Date
- How to Use Overtime to Pay Down Debt Without Leaving Yourself Short
- Debt Snowball or Avalanche When Your Extra Pay Changes Each Month?
Expanded member resource: Workplace Retirement Organizer. Guided exercises with local save, reopen and print controls. Worksheet answers are not automatically calculated. Compare free resources and FSF membership benefits.
Human-reviewed, AI-assisted content; how FSF creates articles.