
The money reached your IRA—but is it invested the way you intended?
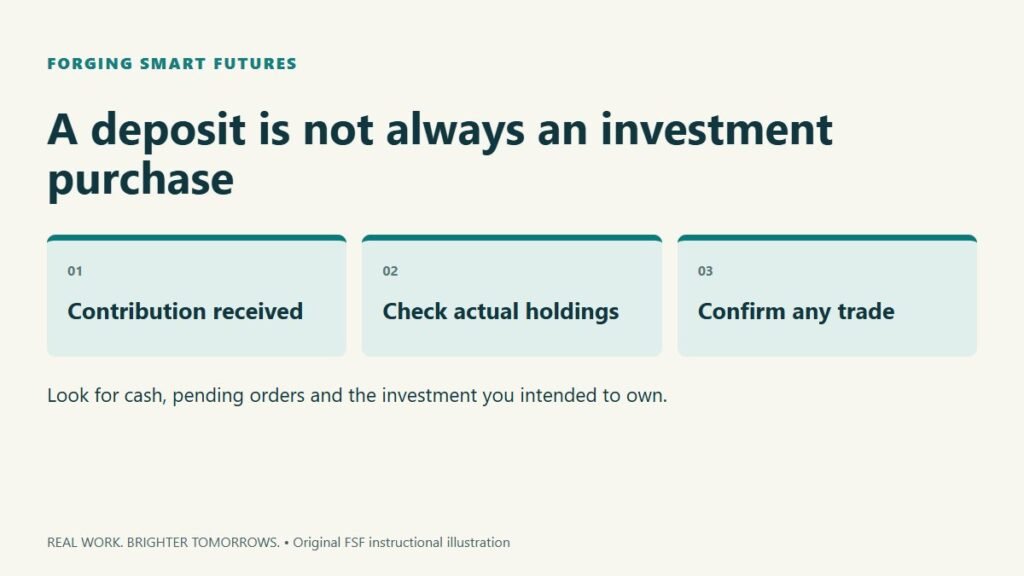
A deposit into an investment account and a purchase of an investment are different events. After contributing, check where the money actually sits. Cash can have a legitimate purpose, but you should know whether holding it was your decision or an unfinished step.
This article is about reading the account, not choosing a security or deciding how much risk you should take.
Follow the money through three records
Look for the contribution or transfer confirmation, the account's current holdings, and any trade confirmation. A transaction labeled “contribution” may confirm that money entered the account without confirming an investment purchase. Automatic contributions and automatic investment instructions should be checked separately.
The SEC's account-statement guidance distinguishes holdings such as cash, stocks, bonds and funds, and discusses cash-sweep arrangements. Your provider's labels and account agreement explain the particular arrangement. Investor.gov statement guide
Do not treat every cash label as identical
An account may use a cash balance, a bank sweep or a money market fund. Identify the actual product, yield information, fees, access conditions and applicable protections. A money market mutual fund is an investment; do not infer bank-deposit insurance from the word “money.” Ask the provider if the statement is unclear.
This is also a reason not to rush into a purchase merely to make the cash line disappear. The next step is matching holdings to a considered plan and time horizon, not choosing whatever appears first in the app.
A fictional account reconciliation
Suppose an account began the period with $2,000 in a fund and no cash. You contributed $300. Ignoring market movement, fees and income for this example, the ending account shows $2,000 in the fund and $300 in cash. The total $2,300 is correct, but the new contribution has not increased that fund position.
If your intention was to invest the contribution, investigate whether an order was never entered, is pending, failed or uses a different schedule. If your intention was to hold cash temporarily, record when you will reconsider. Never submit a duplicate order simply because an interface has not refreshed.
Check the tax-year designation separately
An IRA contribution has eligibility and annual-limit rules; a holding review does not establish that a contribution was allowed. Verify the contribution year shown in the account and use current IRS guidance for the applicable IRA type. Do not confuse a rollover or transfer with a new annual contribution. IRS IRA guidance
Keep confirmation records and ask the provider about an apparent error before moving money. This article deliberately does not quote a yearly limit that could distract from account-specific eligibility.
Make the check repeatable
After a deposit or an automated setup change, record: money received, intended destination, actual holding, transaction status and next review date. Review fees and account activity as well. An annual statement check is useful, but finding a missing recurring instruction earlier can prevent months of misunderstanding.
Use first investing steps to separate goals, account choice and investments, and investment fees to inspect costs. The useful outcome is knowing what you own and why—not simply seeing a larger account total.
Human-reviewed, AI-assisted content; how FSF creates articles.
Editorial attribution: Paul Foster
Published: September 30, 2026 Last reviewed: September 18, 2026