
Medical Bill You Cannot Pay? Review It Before Choosing Financing
The short answer
Confirm what you owe, ask about insurance processing and financial assistance, then compare affordable payment terms. Moving a bill onto a credit product before those checks can change your options and add costs.
The CFPB recommends asking about insurance coverage and available assistance before accepting a medical payment plan or credit card. It also warns about the costs and conditions of these products. CFPB medical financing guidance.
Build a small billing file
Keep the provider bill, dates of service, insurance explanation of benefits where applicable, payment receipts and any estimates or notices. Ask for an itemized bill if the summary is unclear. Check names, dates, duplicate-looking charges and whether insurance has finished processing.
An explanation of benefits describes how a claim was processed; it is not itself a demand for payment. Ask the provider and insurer to reconcile differences rather than assuming the larger number is automatically correct. Keep a call log with date, contact, question and promised next step. CMS guide to an explanation of benefits.
Do not ignore deadlines while a question is open. Ask in writing whether billing or collection activity can be paused during review or an assistance application, and obtain confirmation rather than assuming a pause.
Ask about assistance before borrowing
Request the provider's financial-assistance policy, eligibility criteria, application and deadline. Ask whether it applies to your bill and whether separate clinicians or facilities require separate applications. Having insurance does not by itself answer every assistance question.
If you believe billing protections may apply, contact the insurer, provider or the appropriate official consumer-assistance channel. This article does not determine eligibility or a legal right to a particular adjustment.
Keep copies of what you submit. A requested document or missing signature can hold up a decision even when the underlying financial need is clear.
Calculate the payment you can sustain
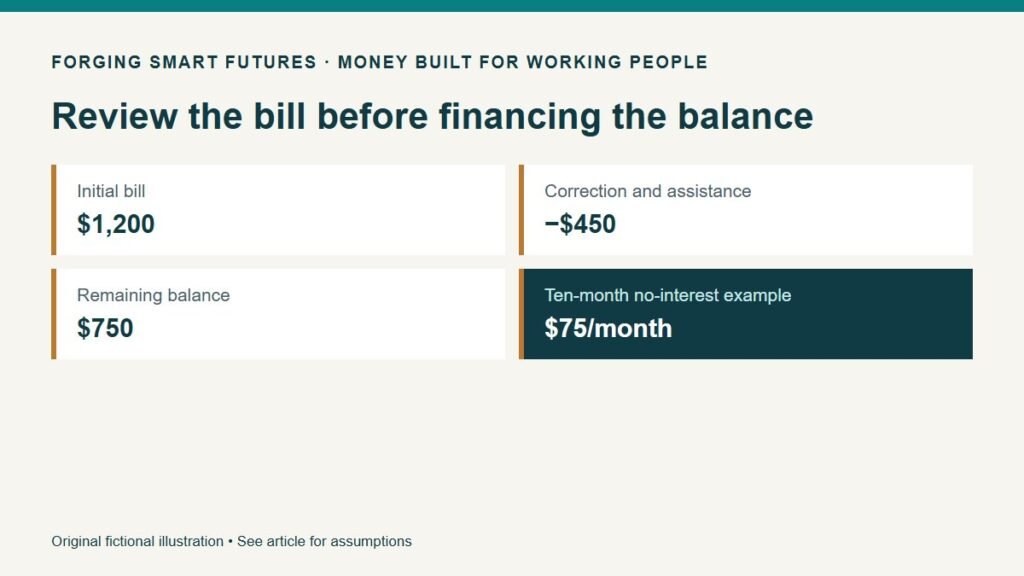
In a fictional example, a $1,200 bill is corrected by $150 and assistance reduces it by another $300, leaving $750. If a provider offers a no-interest ten-month arrangement, the payment would be $75 monthly.
If the household can reliably spare only $50 monthly, the proposed plan still does not fit. A fifteen-month no-interest schedule would equal $50, but that is a request to discuss, not a term the provider must offer. Confirm any agreed arrangement in writing.
Use ordinary income after essential bills and debt minimums. Do not promise a payment that depends on unconfirmed overtime, especially while illness or recovery is affecting work hours.
Read the financing agreement separately
Identify the actual lender, amount financed, interest rate, fees, payment schedule and late-payment consequences. Ask whether “no interest” means interest is waived under stated conditions or deferred and potentially charged later. A promotional minimum payment may not retire the balance by the promotion's deadline.
For a fictional $1,200 balance that must be fully repaid in twelve months to meet a promotion's conditions, equal principal payments would be $100 monthly, assuming no added charges. Paying $60 for twelve months would pay $720 and leave $480 before any interest or fees triggered by the agreement.
Do not assume the lender's approval means the payment is affordable. Compare the whole cost with a direct provider arrangement after assistance decisions are known.
Keep follow-up manageable while working shifts
Set one scheduled billing follow-up period and a reminder before each deadline. If calling during business hours is difficult, ask about a secure message or written process. Share only the information needed through verified provider or insurer channels.
If a collector contacts you, verify the debt and applicable rights through official guidance rather than paying an unfamiliar caller under pressure. Do not rely on claims that every medical debt is automatically removed from credit reports or never collectible.
Your next action
Request the itemized bill and assistance information before applying for financing. Use the FSF bill-calendar guide to test any proposed payment. Existing free and member resources are labeled on the Resources page.
General education, not individualized medical, legal, credit or financial advice. All adjustments and terms are fictional; assistance is not guaranteed. No affiliate relationship is presented.
Editorial attribution: Paul Foster
Published: September 10, 2026 Last reviewed: September 10, 2026
Sources & References
- https://www.consumerfinance.gov/ask-cfpb/what-should-i-know-about-medical-credit-cards-and-payment-plans-for-medical-bills-en-1827/
- https://www.cms.gov/initiatives/your-patient-rights/medical-bill-rights/get-help/medical-bill-guides-resources/how-read-health-insurance-explanation-benefits
Put this into practice
Put balances, dates and written terms in one usable plan. Free Debt & Credit checklist — no membership required.
Related decisions
- Credit Freeze or Credit Monitoring: What Each One Actually Does
- Check Your Credit Before You Need the Next Work Vehicle
- Secured Card or Credit-Builder Loan When Cash Is Tight?
Expanded member resource: Debt Organization and Decision Workbook. Guided exercises with local save, reopen and print controls. Worksheet answers are not automatically calculated. Compare free resources and FSF membership benefits.
Human-reviewed, AI-assisted content; how FSF creates articles.