
A Pension Estimate Is Not a Take-Home Retirement Budget
The short answer
Read the assumptions behind the estimate, identify the payment option and retirement date, then account for taxes, deductions and household expenses. A headline monthly pension figure is not automatically the amount that reaches your bank account or continues to a surviving spouse.
The Department of Labor describes how retirement-plan payment forms and survivor benefits differ by plan type. Your plan documents and administrator are the starting point for your actual options. DOL retirement plan questions.
Label every estimate
Record the estimate date, proposed benefit start date, credited service, pay assumptions, payment form and whether continued work is assumed. A projection at age 65 after several more years of service cannot be substituted for an amount payable if you leave next month.
Ask the administrator to explain any service or earnings record you do not recognize. Keep supporting employment records where available. Correcting a misunderstanding before an election is preferable to discovering it after the household has already committed to retirement spending.
If the plan offers several payment forms, request comparable estimates for the same start date. Comparing different ages and different survivor options in one column hides what caused the difference.
Compare household protection, not just the largest check
A payment for one person's lifetime may differ from a joint-and-survivor option. Ask what happens after either person dies, whether any guaranteed period applies, and whether consent or an irreversible election is involved. Do not interpret a smaller monthly amount as an unnecessary fee without understanding what it provides.
This article does not recommend an election or assume every plan offers the same choices. A spouse's income, health coverage and other resources can matter. Bring the actual documents to an appropriately qualified adviser when the choice has long-term consequences.
Convert the estimate to available cash
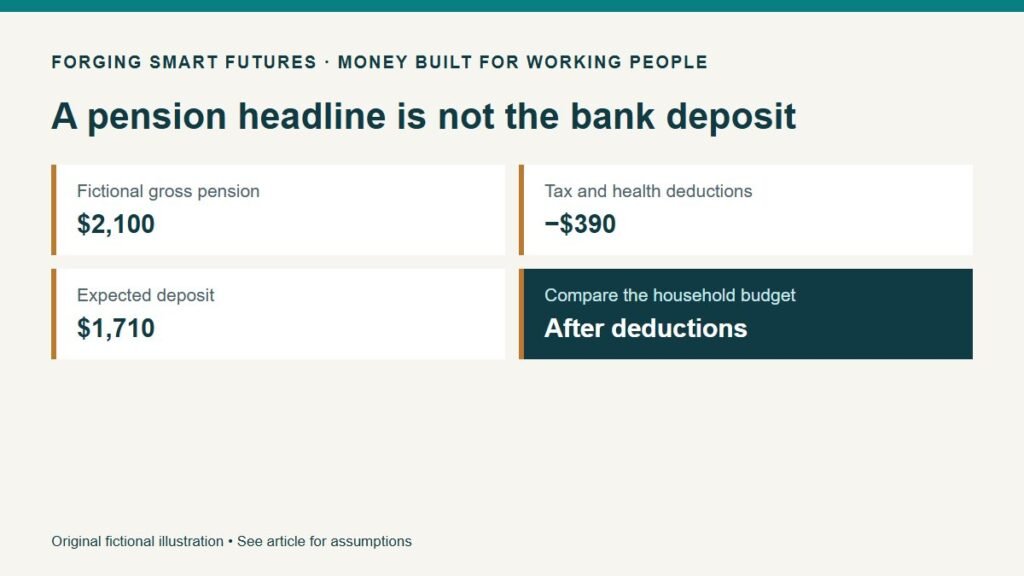
In a fictional illustration, the chosen payment option shows $2,100 per month before deductions. Estimated tax withholding is $210 and a retiree-health deduction is $180. The resulting deposit is $1,710.
These deductions are invented, not pension tax rates or health-premium quotes. Actual withholding is not necessarily the final tax liability. The example simply shows why a $2,100 headline should not be used as a $2,100 grocery-and-bills budget.
Suppose another verified household income source provides $1,200 after relevant deductions. Total available cash is $2,910. Against a $3,200 monthly spending estimate, the gap is $290, or $3,480 over a year before any changes.
Include costs that do not arrive monthly
Add insurance renewals, vehicle replacement, home repairs and other irregular expenses using a reasonable planning allowance. Separate premium costs from possible deductibles and uncovered expenses. A budget with only utilities and groceries can appear balanced while larger commitments are missing.
Ask whether pension payments have any cost-of-living adjustment, what determines it and whether it is guaranteed. Do not assume the benefit rises just because prices do. If a payment stays fixed, test how the budget handles higher costs without inventing a precise future inflation forecast.
Keep timing and other benefits separate
Confirm when the first payment arrives, any processing steps and how the final paycheck lines up with retirement income. Social Security and Medicare have their own eligibility and enrollment rules; a pension start date does not settle them.
If a lump sum is offered, compare it with ongoing payments only after understanding taxes, investment responsibility, survivor considerations and the plan's terms. Dividing the lump sum by the monthly pension is not a complete decision method because it omits longevity, investment risk and other differences.
Your next action
Ask for a written estimate with the payment form and start date clearly identified. Build the household budget from expected deposits and separately listed deductions. Use the FSF bill-calendar method to check the transition and the Resources page for existing planning materials.
General education, not individualized pension, investment, tax or legal advice. All amounts are fictional. No benefit election, future payment or affiliate relationship is endorsed.
Editorial attribution: Paul Foster
Published: September 10, 2026 Last reviewed: September 10, 2026
Sources & References
- https://www.dol.gov/agencies/ebsa/about-ebsa/our-activities/resource-center/faqs/retirement-plans-and-erisa
Put this into practice
Turn plan documents and old statements into specific next steps. Free Retirement checklist — no membership required.
Related decisions
- Retiring Before Medicare: Put Health Coverage in the Plan
- Social Security at 62 or Later: Questions for Workers in Physical Jobs
- How to Read Your 401(k) Match When Your Pay Includes Overtime
Expanded member resource: Workplace Retirement Organizer. Guided exercises with local save, reopen and print controls. Worksheet answers are not automatically calculated. Compare free resources and FSF membership benefits.
Human-reviewed, AI-assisted content; how FSF creates articles.