
Open Enrollment for Shift Workers: A Practical Comparison Checklist
The short answer
Compare the coming year's options using your household's likely needs, total costs and access to care, then submit and verify the elections before the actual deadline. Last year's selection may still fit, but it should be a checked decision rather than an unnoticed default.
Use the Summary of Benefits and Coverage to compare health-plan features on a consistent basis. HealthCare.gov explains that this document summarizes costs and coverage and includes standardized examples; those examples are not your personal cost estimate. Summary of Benefits and Coverage guidance.
Build the packet before the deadline week
Collect the enrollment deadline and time zone, effective date, employee premium schedule, coverage summaries, provider directory, drug information and instructions for dependents. Include dental, vision, disability and other offered benefits as separate decisions rather than assuming they all follow the medical election.
For rotating shifts, plan when you can contact benefits staff while they are available. Submit questions in writing early enough for an answer. An overnight shift ending on the deadline morning is a poor time to discover that the portal requires a password reset.
Convert payroll prices to annual prices
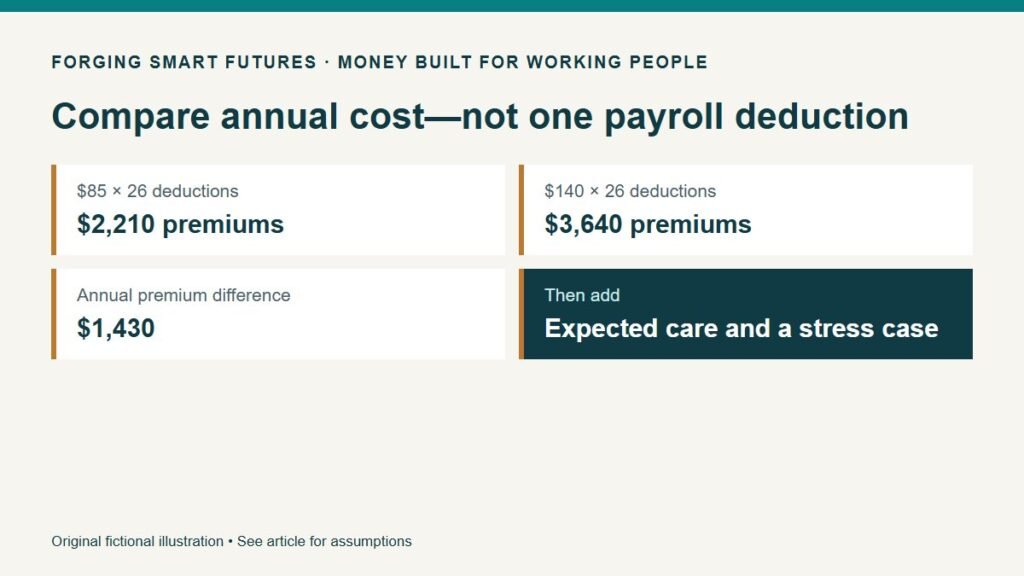
A fictional option costs $85 each biweekly paycheck with twenty-six deductions: $2,210 annually. Another costs $140 per deduction: $3,640 annually. The premium difference is $1,430.
Do not multiply a biweekly amount by twenty-four simply because there are twelve months. Confirm how many deductions your employer actually takes, including whether some pay periods have no deduction. Compare the same coverage tier and household members.
If expected covered-care spending is $1,500 under the first option and $500 under the second, the simplified premium-plus-care totals are $3,710 and $4,140. The higher-premium option is $430 more in that specific scenario. Different care needs can reverse the result; these figures are invented and omit other costs.
Test a higher-use year too
Record the deductible, copayments, coinsurance and applicable out-of-pocket limits. Ask what counts toward each and what does not. Premiums are separate from cost sharing. Noncovered services and some out-of-network expenses may sit outside the limit you are using.
Avoid adding the full deductible on top of the out-of-pocket maximum as if both are always separate amounts. Use the plan's definitions and coverage examples to understand the relationship, then ask for clarification where needed.
Keep employer account contributions separate and check when they arrive and how they can be used. A contribution deposited throughout the year may not solve a large bill in January in the same way as money available on day one.
Check access around your real schedule
Verify important doctors, facilities and prescriptions in the new plan. Ask about appointment availability, after-hours care and locations near work or home. A nominally covered service may still be inconvenient if every appointment conflicts with your shifts.
Check dependent eligibility and any other coverage available to the household. Compare complete household arrangements rather than assuming everyone must be on the same employer's option. Benefits staff can explain the offered rules; they cannot substitute for checking the other plan's terms.
Finish with a saved confirmation
Before submitting, review coverage tier, dependents, account elections and beneficiaries where relevant. Save the confirmation and the documents used for the decision. Record the effective date and which elections require a new choice each year.
After coverage begins, check payroll deductions and enrollment records. Report a mismatch promptly through the employer's process. Saving a screenshot of an intended choice is useful evidence, but verify that the election was actually submitted and accepted.
Your next action
Compare two plausible health-plan scenarios and list unresolved questions before choosing. Add the resulting paycheck deductions to the FSF variable-pay budget. Existing free and member worksheets are identified on the Resources page.
General education, not individualized insurance, medical, tax or financial advice. All prices and care costs are fictional. No plan or affiliate relationship is endorsed.
Editorial attribution: Paul Foster
Published: September 10, 2026 Last reviewed: September 10, 2026
Sources & References
- https://www.healthcare.gov/health-care-law-protections/summary-of-benefits-and-coverage/
Put this into practice
Compare written pay, time and benefit terms on the same basis. Free Work & Compensation checklist — no membership required.
Related decisions
- Build a Raise Request Around the Value of Your Work
- Is That Certification Worth the Cost? Compare Time, Pay and Opportunity
- Compare Disability Coverage When Your Pay Depends on Physical Work
Expanded member resource: Total Compensation Decision Workbook. Guided exercises with local save, reopen and print controls. Worksheet answers are not automatically calculated. Compare free resources and FSF membership benefits.
Human-reviewed, AI-assisted content; how FSF creates articles.