
Changing Jobs? Compare Your Old 401(k) Options Before Moving Money
The short answer
Collect the old plan's balance, tax sources, fees, investment options and any loan details before requesting a payment. Compare the available destinations and the consequences of taking cash. Moving money is a separate decision from choosing investments, and receiving a check personally can create avoidable complications.
Common possibilities include leaving assets in the old plan if allowed, transferring eligible money to a new employer plan that accepts it, rolling eligible money to an IRA or taking a distribution. Availability and consequences depend on your plan and account details. IRS rollover guidance.
Make an account inventory before a choice
Record vested balance, pre-tax amounts, designated Roth amounts, any after-tax non-Roth amounts, employer stock and outstanding plan loans. Save recent statements and the plan contact information outside the former employer's email system.
Ask for the distribution notice and written instructions. Check whether the plan imposes a response deadline or can distribute a small balance without your preferred election. Do not assume a coworker's rollover experience applies to your balance or departure date.
If employer stock, a loan, a pending domestic-relations order or an early-access strategy is involved, get specialized guidance before moving assets. This general comparison does not resolve those situations.
Compare the destinations on one page
| Option | Questions to resolve |
|---|---|
| Keep the old plan | Is it allowed, what fees apply and can you maintain access and current contact details? |
| New employer plan | Does it accept these funds, when can the transfer occur and what are its costs and options? |
| IRA | What are total fees, investment choices, advice arrangements and relevant legal or tax differences? |
| Cash distribution | What taxes, possible additional tax and lost retirement savings would follow? |
Do not assume an IRA is always cheaper or that a workplace plan always has better investments. Compare actual documents. Ask whether advice is included, optional or tied to a recurring asset-based fee.
Understand the direct-transfer distinction
An eligible direct rollover is paid to the receiving retirement arrangement rather than to you personally. The IRS explains that mandatory withholding associated with a payment to you can be avoided through the appropriate direct rollover process. Confirm the recipient, account type and instructions with both providers.
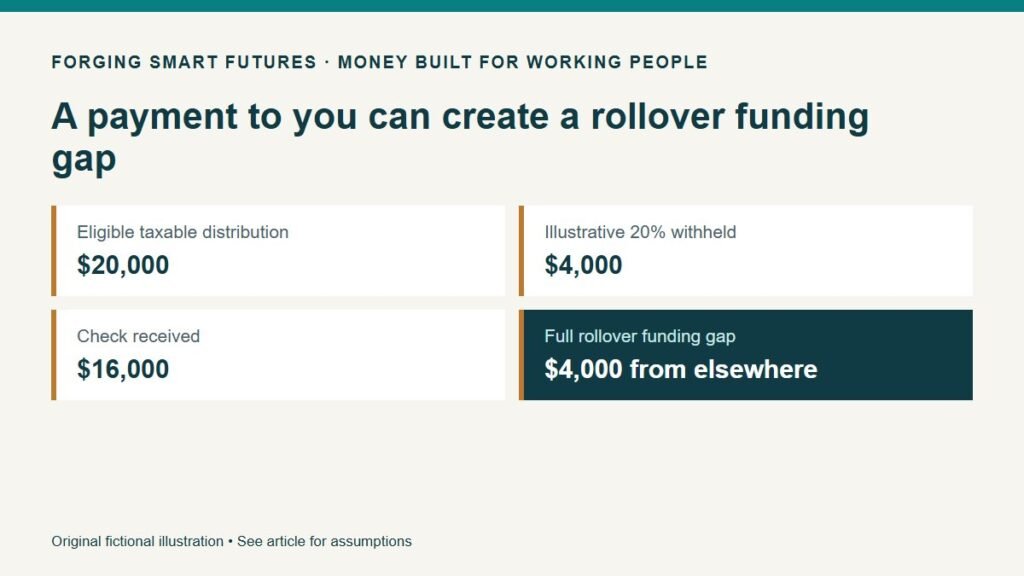
For a simplified fictional example of an eligible taxable employer-plan distribution paid to you, a $20,000 amount subject to 20% mandatory withholding produces a $16,000 check. To roll over the full $20,000 within the applicable deadline, you would need $4,000 from elsewhere. Withholding is not necessarily your final tax bill.
The usual rollover deadline for a payment received personally is sixty days, with exceptions and special rules. Not every distribution is eligible. Do not rely on fixing a mistake later; obtain transaction-specific instructions before requesting the payment. IRS Topic 413 explains withholding and rollover timing.
Keep tax sources and destinations aligned
Moving pre-tax money into a Roth account can be a taxable conversion rather than a tax-free move. Designated Roth and after-tax amounts require appropriate handling. Tell both administrators exactly what the account contains and ask for the expected reporting.
Check the receiving account after the transfer. Verify the amount, tax-source records, fees and investment election. Money arriving in a settlement position does not automatically mean the intended investment purchase occurred. Retain completion records and the tax forms when issued.
Protect the job-transition cash plan
A final paycheck, new payroll start date and benefit changes can create a short-term gap. Identify that separately instead of treating retirement savings as the default bridge. Use the FSF bill-calendar guide to map the transition.
If cashing out feels necessary, compare the immediate need with alternatives and the actual tax consequences with a qualified professional. A smaller account is still retirement money; convenience is not the same as a favorable result.
Your next action
Request the old plan's written options and the new plan's acceptance rules before submitting a distribution election. Review FSF's match guide for your new payroll setup. The Resources page lists existing planning materials, not rollover execution services.
General education, not individualized investment, tax or legal advice. The withholding example is fictional and limited to its stated assumptions. No affiliate relationship is presented.
Editorial attribution: Paul Foster
Published: September 10, 2026 Last reviewed: September 10, 2026
Sources & References
- https://www.irs.gov/retirement-plans/plan-participant-employee/rollovers-of-retirement-plan-and-ira-distributions
- https://www.irs.gov/taxtopics/tc413
Put this into practice
Turn plan documents and old statements into specific next steps. Free Retirement checklist — no membership required.
Related decisions
- Starting Retirement Saving at 45 or 55: Build a Plan From Today’s Numbers
- A Pension Estimate Is Not a Take-Home Retirement Budget
- Retiring Before Medicare: Put Health Coverage in the Plan
Expanded member resource: Workplace Retirement Organizer. Guided exercises with local save, reopen and print controls. Worksheet answers are not automatically calculated. Compare free resources and FSF membership benefits.
Human-reviewed, AI-assisted content; how FSF creates articles.